
The typical American renter now pays $300 to $400 less each month than the typical American with a mortgage, according to the Federal Reserve’s own numbers.
Story Snapshot
- The Federal Reserve found the median rent in 2024 was $1,200 a month, while the median mortgage payment was $1,500.
- Mortgage costs stayed roughly 30 to 40 percent above rent through 2024 in separate federal housing agency estimates.
- Homeowners still hold far more net wealth than renters on average, with some studies putting the gap at 40 times or more.
- The right choice depends on how long someone plans to stay put, not just which monthly number looks smaller today.
What The Latest Government Numbers Actually Show
The Federal Reserve’s 2025 report on household finances laid out the gap in plain dollars. Renters paid a median of $1,200 a month in 2024. Homeowners with a mortgage paid $1,500. A year later, the Fed’s newest data pushed the median mortgage payment to $1,600, while rent barely moved. That widening spread is not a one-time fluke. It shows up across multiple federal and industry sources tracking the same trend.
The Federal Housing Finance Agency ran its own math and found an even sharper divide. In April 2024, the agency estimated that a household moving from a rental into a home they wanted to buy would pay 36 percent more per month for the privilege. Freddie Mac’s research arm found a similar pattern, estimating buyers would pay about $600 more a month than renters, a 32 percent premium. Different agencies, same conclusion: buying costs more right now, month to month.
Why Renting Wins The Monthly Math But Not Always The Long Game
Monthly cost is only half the story, and anyone who has watched a parent or grandparent pay off a house knows it. Homeownership builds equity with every payment. Renters build nothing tangible beyond a receipt. That distinction shows up starkly in wealth studies. Renters hold a median net worth far below homeowners, with one Aspen Institute analysis putting renter wealth at under 3 percent of what homeowners hold.
The Joint Center for Housing Studies at Harvard reached a similar verdict after running the numbers multiple ways. Even when researchers assumed renters took their monthly savings and invested them wisely, owning still came out ahead in wealth accumulation over time. That finding challenges a popular argument that renting plus disciplined investing beats buying. The math says otherwise for most households over a long enough horizon.
Not Every Market Tells The Same Story
Location changes everything here. A wealth study out of Canada found renters in Montreal actually built 48 percent more wealth than owners over nineteen years, and nationally renters and owners finished nearly tied. That is a sharp contrast to the wide American gaps cited above. High-price coastal markets, tight rental supply, and local tax rules all shift the calculation. A national average hides a lot of local variation that matters more to any one family’s decision.
Census Bureau figures released this year add another wrinkle. Homeowners’ costs barely budged between the 2015-2019 and 2020-2024 periods, while renters saw their median payment climb $100 to $1,413. In roughly one out of five U.S. counties, renters now pay more than mortgaged owners do. That reverses the national pattern in specific pockets of the country, proof that “rent versus buy” cannot be answered with one blanket rule.
What This Means For A Family Weighing The Decision Today
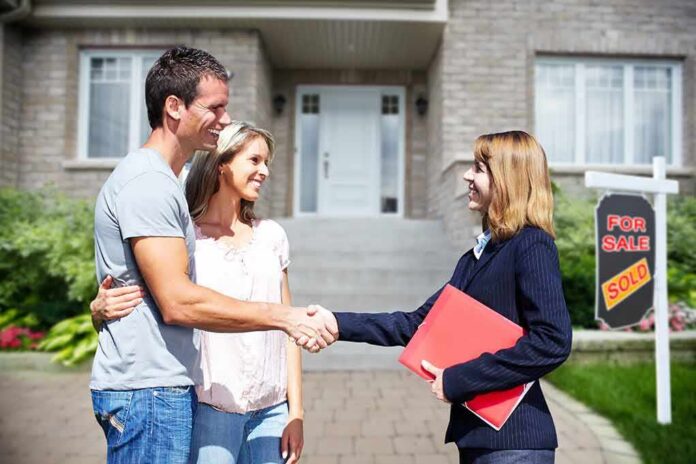
None of this data settles the debate for every household, and it should not. A young professional who might relocate for work in two years faces a different equation than a couple planting roots for thirty. Renting offers flexibility and a lower entry cost right now. Buying locks in a payment, builds equity, and historically rewards patience. The honest answer is that both sides of this argument are backed by real numbers, and the right one depends on the life being built, not just the spreadsheet.
ICYMI: The Long-Term Cost of Renting vs. Buying: You’ve probably asked yourself lately: Is it even worth trying to buy a home right now? It’s a question a lot of people are asking. https://t.co/L5lk7WI10R pic.twitter.com/VVoEmBKWoq
— Gina Arigna and Amit Singh- Arigna Team (@Arigna_Team) September 18, 2026
Families should treat this like the serious financial decision it is, not a slogan from a realtor or a landlord. Pull the local numbers. Compare actual rent listings against actual mortgage quotes in the specific neighborhood being considered. The national averages from the Fed and Freddie Mac are a starting point for the conversation, not the final word on any one family’s driveway.
Sources:
youtube.com, nbc.ca, fhfa.gov, federalreserve.gov, businessinsider.com, census.gov, ca.finance.yahoo.com, assets.cmhc-schl.gc.ca