
A family that tracks every dollar, saves before it spends, and buys the right insurance rarely gets blindsided by a crisis the same way one living paycheck to paycheck does.
Story Snapshot
- Financial advisers recommend saving three to six months of living expenses as a core emergency buffer.
- A written budget, debt control, and automatic savings transfers form the backbone of financial resilience.
- Matching investments to your time horizon protects short-term goals from stock market swings.
- Health savings accounts, insurance, and retirement plans extend financial wellness into long-term health protection.
The Core Strategy Behind Financial Resilience
Building financial security starts with a plan, not luck. Guidance on securing a family’s financial future points to four pillars: setting clear goals, building a monthly budget, saving consistently, and diversifying investments. Financial advisers recommend keeping three to six months of living expenses in reserve, a buffer meant to absorb job loss, medical bills, or car repairs without forcing a family into high-interest debt.
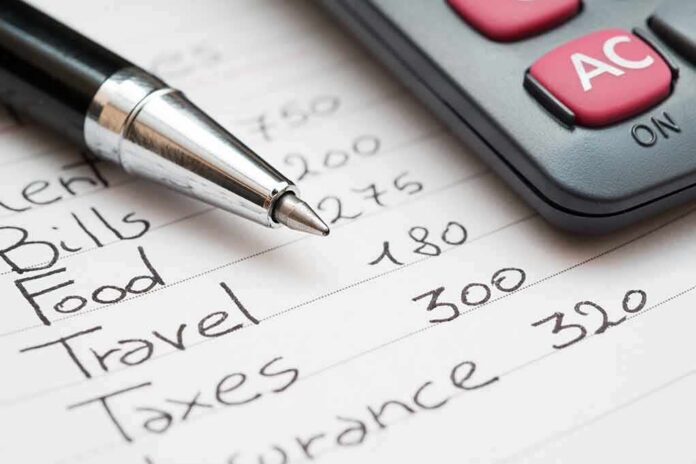
None of this requires a finance degree. Tracking spending for one or two months reveals where money actually goes, which makes building a realistic budget possible. From there, the plan gets adjusted to match real income and real costs, and automatic transfers move savings into a separate account before anyone is tempted to spend it.
Why Money Stress Spills Into Everything Else
Money worries do not stay contained to a bank statement. Guidance on achieving calm around personal finances notes that a clear strategy eases burdens, helps bills get paid on time, and lowers debt loads, all of which improve a person’s day-to-day outlook. An emergency fund in particular is credited with relieving the kind of chronic stress that builds when every unexpected expense feels like a crisis.
That link between money and mood shows up in broader research too. A systematic review of forty observational studies found financial stress positively associated with depression in adults, a pattern especially pronounced among people with lower incomes. The association is well documented, even though the studies involved cannot isolate every contributing factor behind it.
Matching Investments To Time Horizon And Risk
Not every dollar belongs in the stock market. Guidance aimed at younger savers recommends holding cash, not stock investments, for any goal within five years, since markets can drop sharply with little warning. The same guidance puts emergency savings and clear goal-setting ahead of investing, arguing that a cushion has to exist before riskier assets make sense.
Health Savings, Insurance, and Retirement As Protection
Wellness investing extends past a brokerage account. Health savings accounts, health insurance, life insurance, and retirement plans all function as financial protection against future health needs, according to guidance built around health investments in your twenties. Each tool shifts risk away from a single bad month and onto a structure built for the long haul.
Smarter shopping habits reinforce the same discipline. Guidance connecting smart shopping to a balanced lifestyle treats mindful spending as part of the same wellness equation as budgeting and saving, rather than a separate behavior. A family that shops with intention frees up money that would otherwise vanish into impulse purchases, strengthening the same emergency fund the other strategies depend on.
What Broader Research Adds To The Picture
Independent research on workplace wellness programs offers an important nuance worth understanding. A large randomized trial at a US warehouse retail company found wellness programs raised exercise rates and improved some self-reported health behaviors, but did not produce significant changes in actual medical spending or clinical health measures after 18 months. A separate university-based trial over two years found no significant differences in biometrics or medical use among employees invited to join a wellness program.
Those findings do not undercut the value of personal budgeting, saving, and insurance. They point to a narrower truth: broad wellness branding does not automatically translate into measurable health or financial gains, but the specific tools recommended here, an emergency fund, a working budget, insurance matched to risk, have a direct and traceable link to reduced financial stress. The payoff comes from the specific habit, not the label.
Sources:
artofhealthyliving.com, jamanetwork.com, pmc.ncbi.nlm.nih.gov, journals.sagepub.com